The 145% tariffs imposed by the United States on Chinese goods have significantly impacted China’s economy, particularly its export-oriented manufacturing sector. Based on available information, here’s an analysis of the effects and the situation regarding factories and video-sharing platforms:
Economic Impact of Tariffs on China
1 Plunge in Exports to the U.S.:
◦ Analysts predict that China’s shipments to the U.S. could drop by as much as 80% over the next two years due to the tariffs. This is critical because, despite exports to the U.S. accounting for only about 3% of China’s GDP, they support millions of jobs, with estimates suggesting 10–20 million workers are involved in U.S.-bound export businesses.
◦ Small factories, especially in southeastern hubs like Guangzhou, are struggling with canceled orders from American customers, leading to financial losses and reduced production. Many of these factories operate on thin profit margins, making them highly vulnerable.
2 Factory Closures and Layoffs:
◦ There are reports of Chinese factories facing severe slowdowns, with some shutting down or scaling back operations. Social media posts on X claim factories are closing en masse and workers are facing unemployment, comparing the impact to or exceeding that of the COVID-19 pandemic. However, these claims lack specific data and should be treated as anecdotal until verified.
◦ The tariffs have disrupted supply chains, and companies are hesitant to invest in new facilities due to uncertainty, potentially leading to further economic stagnation in manufacturing regions.
3 Economic Growth and Employment:
◦ Goldman Sachs revised China’s GDP growth forecast to 4%, citing trade tensions and slower global growth. The loss of export revenue threatens employment, particularly for migrant workers in export hubs.
◦ Chinese businesses face shrinking profit margins, with some logistics and freight companies reporting that tariffs above 35% could wipe out profits entirely.
4 Diversification Challenges:
◦ Many Chinese firms adopted a “China Plus One” strategy, shifting production to countries like Vietnam and Cambodia to mitigate earlier tariffs. However, new U.S. tariffs on these countries (e.g., 32% on Indonesia) have undermined these efforts, leaving companies with limited options.
◦ Relocating supply chains is costly and time-consuming, and alternatives lack China’s infrastructure and scale, making adaptation difficult.
5 Price Increases and Market Shifts:
◦ To cope, some exporters are raising prices for U.S. consumers, which could reduce demand for Chinese goods. Others are halting shipments entirely, particularly for low-margin products like textiles.
◦ China is attempting to pivot to domestic consumption and other markets (e.g., Europe, Southeast Asia), but weak domestic demand and global trade barriers pose challenges.
Abandoned Factories and Video Sharing
• Abandoned Factories:
◦ While there’s no comprehensive data confirming widespread factory abandonment, the economic pressure from tariffs is leading to reduced activity. Factories are not necessarily “abandoned” in the literal sense but are idling or operating at reduced capacity due to canceled orders and financial strain. For example, clothing factories in Guangzhou report losses from unsold inventory.
◦ Videos circulating on platforms like YouTube, referenced in X posts, claim to show factory closures and unemployment, but these are often unverified and may exaggerate the situation for dramatic effect. Without specific evidence, such claims should be approached cautiously.
• Video Sharing Platforms:
◦ The query mentions “video sharing factories abandoned,” which may refer to content on platforms like Douyin (China’s TikTok) or YouTube showing struggling factories. There’s no direct evidence that tariffs have impacted video-sharing platforms themselves, but they are being used to document economic fallout. For instance, X users cite “mini-documentaries” on Chinese platforms discussing tariff effects, describing conditions worse than during COVID-19.
◦ These videos reflect public sentiment and may amplify perceptions of economic distress, but they don’t provide quantitative data on factory closures. The Chinese government’s censorship could also limit how much negative economic content is shared domestically.
Broader Context and Chinese Response
• Retaliatory Tariffs:
◦ China responded with an 84% tariff on U.S. goods (later raised to 125% in some cases), escalating the trade war. This tit-for-tat approach risks further isolating both economies but hurts China’s export-driven model more immediately.
◦ Beijing has signaled openness to negotiations but insists on “equal footing,” showing reluctance to concede ground.
• Long-Term Implications:
◦ Some analysts suggest tariffs could force China to restructure its economy toward domestic consumption, but this shift is slow and fraught with challenges given weak consumer demand.
◦ China’s manufacturing dominance, built on cheap labor and vast infrastructure, remains resilient in high-tech sectors like AI and robotics, but low-margin industries (e.g., textiles, toys) are hit hardest.
Critical Perspective
The establishment narrative, as reflected in sources like The New York Times and CNBC, emphasizes the tariffs’ immediate harm to Chinese exporters and U.S. consumers, predicting higher prices and disrupted supply chains. However, this view may downplay China’s adaptability—its pivot to advanced manufacturing and non-U.S. markets could mitigate long-term damage. Conversely, X posts often sensationalize factory closures, lacking hard evidence. The truth likely lies in between: tariffs are causing significant but uneven disruption, with low-margin factories suffering most, while China’s broader industrial base endures.
Conclusion
The 145% tariffs have strained China’s economy by slashing U.S. exports, squeezing factory profits, and threatening jobs, particularly in manufacturing hubs. While videos and social media highlight factory slowdowns, claims of mass abandonment are unverified and likely overstated. China faces pressure to diversify markets and boost domestic consumption, but its manufacturing resilience suggests it won’t collapse overnight. For precise data on factory closures, more primary evidence—like government reports or industry surveys—would be needed, but such information is scarce due to China’s controlled media environment.
H.R. 1 Also known as, the big beautiful bill has past Congress and is currently in the Senate. It’s a reconciliation bill, which means if they’re going to alter existing laws and rules and it doesn’t require a 60 vote in the Senate as votes like this can only happen three times in a fiscal year.
This bill will benefit small businesses, farmers and agricultures, People who work in FAA military military/defense/defense contractors and many more including taxpayers, earning less than $500,000 a year.
In hindsight, it looks like it’s Washington as usual. I’m talking about more spending less cutting and not keeping to their promises of cutting waste.
However, when you read over the bill, you’re gonna find that there’s $1.7 trillion in cuts more than anytime after 2005. And there’s a lot of rule changes with existing laws that go against businesses because of environmental impacts brought on by the Democrats and environmental groups.
There’s also claims that will be tax breaks ...
Big food wants you to have cereal for dinner as a alternative to what you would normally have. So I tired it and was not a fan.
In this must-watch video, we put two iconic syrup brands head-to-head in an epic taste test battle - Pearl Milling Co. and Aunt Jemima. Which syrup reigns supreme?
We'll compare and contrast the flavors, textures, and overall taste experience of these two popular syrups. Get an insider look at the judging process as our panel of food experts meticulously analyzes and scores each syrup.
You'll get the full rundown on:
Flavor profiles (sweetness levels, notes of vanilla, maple, etc.)
Consistency and mouthfeel
Appearance and bottle design
Cost and value for money
But the real question is - who will be crowned the ultimate syrup champion? Pearl Milling Co. or Aunt Jemima? Watch to the end to find out the surprising verdict!
#syrups #pancakesyrup #foodreview #tastetestchallenge #pearlmillingco #auntjemima #breakfastfoods #maplesyrup #foodbattle
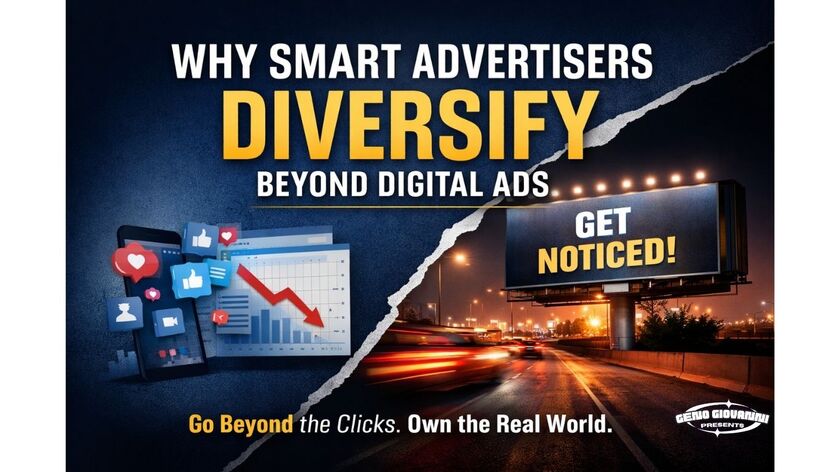
GGP makes it simple to plan and book digital billboard campaigns market by market — so you know exactly where your dollars go before you spend. https://www.genogiovannipresents.com/selfservice
Many businesses reach the same inflection point: digital metrics look active, but business outcomes flatten. Clicks may rise. Impressions may increase. Yet revenue growth, market visibility, and customer acquisition often fail to scale in proportion to spend.
That gap is one reason diversification has become a practical media strategy rather than a branding luxury.
Digital advertising remains useful, especially for search intent, retargeting, and direct response. But it also faces structural limitations. Average display click-through rates remain low, ad fraud continues to drain significant spend from the online ecosystem, and privacy controls have reduced the precision advertisers once relied on for tracking and targeting.
In parallel, out-of-home advertising continues to hold strategic value because it solves a different problem.
OOH is not primarily a click medium. It is a visibility medium.
It places the brand in public space, in commuting patterns, in retail corridors, and in repeated real-world exposure. Recent OOH industry materials show high audience notice levels, and current market guides continue to position digital out-of-home as a growing segment of the broader OOH market.
That does not mean every billboard impression equals perfect attention. It does mean OOH is not exposed to bot-click fraud in the same way digital media is. It also means the medium cannot be skipped with a browser extension or filtered out of a social feed. That distinction matters when brands want durable local visibility.
For advertisers, the key shift is this:
The question is no longer digital or outdoor.
The better question is which part of the funnel each channel should own.
A stronger media mix often looks like this:
Google Ads for demand capture
Paid social for engagement and remarketing
OOH / DOOH for reach, frequency, and geographic dominance
Modern digital out-of-home also gives advertisers more flexibility than legacy outdoor buying. Current OOH materials highlight capabilities such as dynamic creative, scheduling by time or context, and centralized campaign management across multiple screens.
For a regional advertiser, that creates a more balanced system:
digital channels capture active interest,
outdoor builds memory and repeated exposure,
and the combination reduces dependence on any one platform’s pricing, targeting rules, or algorithm changes.
Bottom line:
Diversification is not an anti-digital argument. It is a risk-management and market-presence argument.
Businesses that rely exclusively on platform-based attention are vulnerable to rising costs, measurement volatility, fraud, and policy changes. Businesses that combine digital with out-of-home are better positioned to sustain visibility, reinforce recall, and defend share of attention in the physical market.
Click-through rates (low engagement in display advertising)
WordStream reports average Google Display Network click-through rates around ~0.46%, indicating the majority of impressions do not generate user action.
https://www.wordstream.com/blog/ws/2016/02/29/google-adwords-industry-benchmarks
Ad fraud and invalid traffic in digital advertising
Juniper Research estimates advertisers lose approximately $84 billion annually to ad fraud, highlighting systemic inefficiencies in digital media buying.
https://www.juniperresearch.com/press/press-releases/ad-fraud-costs-to-advertisers-to-reach-84bn
Privacy changes impacting tracking and attribution
Apple introduced App Tracking Transparency (ATT), limiting cross-app tracking and reducing advertisers’ ability to measure and target users with the same precision as before.
https://developer.apple.com/app-store/user-privacy-and-data-use/
Out-of-home (OOH) reach and visibility
Out of Home Advertising Association of America reports that a large majority of U.S. adults are reached by OOH advertising weekly, reinforcing its role as a high-reach, real-world media channel.
https://oaaa.org/Insights/OOH-Fact-Sheet.aspx
Growth of digital out-of-home (DOOH)
Out of Home Advertising Association of America notes that roughly one-third of OOH revenue is now digital, with continued growth driven by programmatic and dynamic capabilities.
https://oaaa.org/news/new-study-finds-digital-out-of-home-advertising-surpasses-other-media-in-driving-favorability-and-action-among-consumers/
Cross-channel effectiveness / media mix importance
Nielsen research consistently shows that combining channels (including OOH with digital) improves overall campaign effectiveness and brand recall.
https://www.nielsen.com/insights/